Legal Help Hub
Reported for Pension Fraud as a Trustee: How Serious is This?


Introduction
Yes, you could face a criminal investigation or regulatory action if you transferred occupational pension scheme money to support your company, even if you have since repaid the full amount.
However, a report of pension fraud does not automatically mean you have committed fraud or that prosecution will follow.
The Pensions Regulator can investigate breaches of pension investment rules and, in serious cases, pursue criminal proceedings.
If you are both a company director and a pension scheme trustee, your responsibilities under each role may also be examined separately.
What matters is whether the transfer was permitted under the rules governing your scheme, what authority you had to make it, and what steps you took to repay the money.
How Serious Is an Allegation of Pension Fraud?
A report that you misused pension scheme funds will be taken seriously by The Pensions Regulator, even if you intended to protect the business.
If your transfer breached the employer-related investment rules, the Regulator may pursue criminal proceedings, impose regulatory sanctions or refer the matter to the police.
The Pension Schemes Act 2021 also introduced criminal offences concerning the management of occupational pension schemes, increasing the potential liability of trustees, directors and others involved in relevant decisions.
However, not every breach of pension investment rules amounts to fraud. A separate fraud allegation depends on whether the evidence supports the elements of that offence.
The Pensions Regulator’s published enforcement policy generally reserves criminal prosecution for the most serious conduct.
Whether your actions meet that threshold depends on what you transferred, whether you had authority, how scheme members were affected and how the matter was reported.
An accountant acting as trustee and administrator of a pension scheme received a prison sentence of more than three years after using scheme funds to make prohibited loans.
This does not mean you will face the same outcome, but it shows why you should seek legal advice promptly.
Can an Employer Borrow Money From Its Occupational Pension Scheme?
Whether you were allowed to transfer money to your company depends on the type of pension scheme, the applicable restrictions and whether an exemption was available.
The general prohibition and the 5% limit
The Pensions Act 1995 prohibits trustees of occupational pension schemes from making loans to the employer except in very limited circumstances.
The employer-related investment rules impose a separate restriction: at any point in time, no more than 5% of the current market value of scheme assets may be invested in employer-related investments.
Employer-related investments include loans to the employer, shares or other securities issued by the employer, and investments in any person connected with or associated with the employer.
A transfer of scheme money to the employer that goes beyond the 5% limit, or that takes the form of a loan where no lawful exception applies, will breach these rules.
When a loan may be permitted
A small self-administered scheme (SSAS) may be able to lend money to its sponsoring employer, provided the relevant pension scheme and tax requirements are satisfied.
HMRC rules allow qualifying employer loans subject to strict conditions.
These include:
- The loan must not exceed 50% of the scheme’s net assets.
- It must be secured by an appropriate first charge over sufficient assets.
- Interest must meet HMRC’s minimum requirement.
- The loan must be repayable within five years in the required instalments.
If you fail to satisfy these conditions, the loan may be treated as an unauthorised payment for tax purposes.
However, meeting HMRC’s loan conditions does not automatically establish compliance with every other pension law requirement.
Your scheme’s legal status and the rules applicable to the transfer must also be checked.
The small scheme exemption
Certain schemes that meet the statutory definition of a small scheme are exempt from employer-related investment restrictions.
This is a specific legal category, not an exemption available to every small pension arrangement.
If you were acting as a trustee of a SSAS or another small scheme, your solicitor should establish whether it qualified for the relevant exemption when the transaction occurred.
Your scheme type, the date of the transfer and the terms of the arrangement will all affect the legal assessment.
Does Full Repayment Prevent a Pension Fraud Prosecution?
No. Repaying the money in full does not automatically prevent prosecution or make an earlier prohibited transfer lawful.
If you breached the employer-related investment rules when you moved the funds, repayment does not erase the original breach.
However, the fact that you repaid the full amount may still be important when your conduct is assessed.
The Pensions Regulator considers several factors when deciding whether to take criminal or regulatory action. These include:
- Whether scheme members suffered financial harm.
- The effect on scheme funding.
- Whether other trustees or the Regulator were kept informed.
- Whether the transfer was properly authorised.
- Whether relevant reporting obligations were met.
- How openly and promptly you responded once concerns were raised.
The Regulator may also consider whether anyone obtained significant financial gains at the scheme’s expense or whether your actions showed serious disregard for members’ interests.
If you repaid the money promptly, ensured the scheme suffered no lasting loss and cooperated with the relevant authorities, those circumstances may support representations on your behalf.
However, they do not guarantee that charges will be avoided.
Pension Fraud: Trustee Moved Scheme Money and Repaid It
What Are Employer-Related Investment Rules and What Happens When They Are Breached?
Employer-related investments under the Pensions Act 1995 include certain shares, securities, property interests and loans involving the sponsoring employer or connected businesses.
The restrictions are intended to protect pension scheme assets from excessive exposure to the employer’s financial position.
If you agreed to an investment that breached the applicable restrictions, you may face criminal liability under the Pensions Act 1995.
This can apply even if you did not personally benefit from the transaction.
Your intention to keep the company trading does not automatically remove liability, although the circumstances may be relevant to how the matter is handled.
A conviction for breaching employer-related investment restrictions can result in a fine, imprisonment or both.
The Pensions Regulator may also impose regulatory financial penalties, subject to the applicable enforcement rules.
Where a breach occurs, there may be obligations to report it and disclose relevant information in the scheme’s annual report.
If you are unsure whether the transfer was permitted, your solicitor can examine the scheme documentation, the investment rules and the authority under which you acted.
The Conflict Between Your Director and Trustee Roles
If you were both a director of the company and a trustee of its pension scheme, you had responsibilities in two different capacities.
As a director, you may have been trying to protect the company from financial failure.
As a trustee, you were responsible for protecting pension scheme assets and acting in accordance with the interests of scheme members and the applicable rules.
These responsibilities can come into conflict when pension money is transferred to support the employer.
For example, using scheme funds to meet urgent business expenses may have seemed necessary to keep the company operating. However, your trustee responsibilities required you to consider whether that use of pension assets was lawful and appropriate.
Investigators may examine how you balanced those responsibilities, who approved the transfer and whether you recognised the potential conflict.
The conflict also affects how you should respond now.
Advice provided to you as a company director may not fully address your personal exposure as a trustee. Similarly, advice obtained by the pension scheme collectively may not protect your individual legal position.
You should obtain independent advice that considers both roles and is given specifically to you, rather than to the company or scheme.
Will The Pensions Regulator or the Police Investigate Pension Fraud?
Both The Pensions Regulator and the police have jurisdiction to investigate conduct involving pension scheme assets, and their investigations can run in parallel.
The Regulator has its own criminal prosecution powers and does not need to refer a matter to the police to bring criminal proceedings.
It can also pursue regulatory sanctions, including contribution notices and fines, through separate civil and regulatory proceedings.
The Pension Schemes Act 2021 strengthened the Regulator’s investigative and prosecutorial powers.
The Regulator can require information, interview individuals under caution and bring prosecutions in the Crown Court.
A report made to the Regulator does not prevent the police from also opening a pension fraud investigation, particularly if the conduct alleged involves elements of dishonesty that could support a separate fraud charge.
You should not assume that the matter will be handled only by one authority or that contact from one body means the other will not become involved.
If you receive any communication from either the Regulator or the police, or if you have reason to believe that a report has been made, you should speak to a solicitor before responding.
Can a Pension Fraud Matter Be Resolved Without Prosecution?
Yes. Some pension scheme breaches are dealt with through regulatory enforcement, corrective action or agreed arrangements rather than criminal prosecution.
The Pensions Regulator generally reserves criminal proceedings for the most serious conduct.
Where a breach was not deliberately dishonest, scheme members suffered no lasting financial harm, the matter was disclosed promptly and full repayment has taken place, there may be grounds for constructive engagement with the Regulator.
However, these circumstances do not automatically prevent prosecution.
Whether a regulatory outcome is possible depends on the seriousness of the breach, the evidence and the Regulator’s assessment of your conduct.
If a police investigation is also underway, any representations to the Regulator should be carefully coordinated with your criminal defence strategy.
Statements you make to one authority may become relevant to another investigation.
Your solicitor can advise whether an agreed regulatory outcome is realistic and how best to approach the authorities.
Facing Legal Issue?
Speak to one of our Fraud and Financial Crime Defence Specialists for confidential advice on your position and next steps.
Strictly Confidential and No Obligation
Penalties and Consequences for Pension Fraud
The penalties that may follow an employer-related investment breach depend on whether the matter is pursued as a criminal prosecution, through regulatory action or both.
A criminal conviction for pension fraud or breach of the employer-related investment rules carries the possibility of an unlimited fine, imprisonment or both.
There is no Sentencing Council guideline specific to this offence category, which means the sentencing court has broad discretion.
The 2019 enforcement outcome, in which a trustee received a custodial sentence of more than three years for using scheme funds to make prohibited loans, illustrates that the courts have been willing to impose immediate custody for serious breaches.
The Pensions Regulator can also impose regulatory financial penalties for breaches of pension legislation.
You may face disqualification from acting as a pension scheme trustee in the future if the relevant legal grounds are established.
If your scheme made a loan that HMRC treats as an unauthorised employer payment, tax charges may also arise. The precise charges and who must pay them depend on the transaction and the applicable pension tax rules.
In addition, the scheme may seek to recover losses caused by a breach of your trustee duties.
Depending on the circumstances, the Regulator may have powers to require financial support or restoration of scheme assets.
Although you have repaid the money, your solicitor should assess whether any interest, investment loss, tax charge or other outstanding liability remains.
What to Do Now: Preserving Evidence and Seeking Advice
If you have been reported for pension fraud or misuse of scheme assets, the steps you take now may affect how the investigation develops.
Your immediate priorities are to preserve relevant records and obtain independent legal advice before responding in detail to the Regulator or police.
Documents to locate and preserve
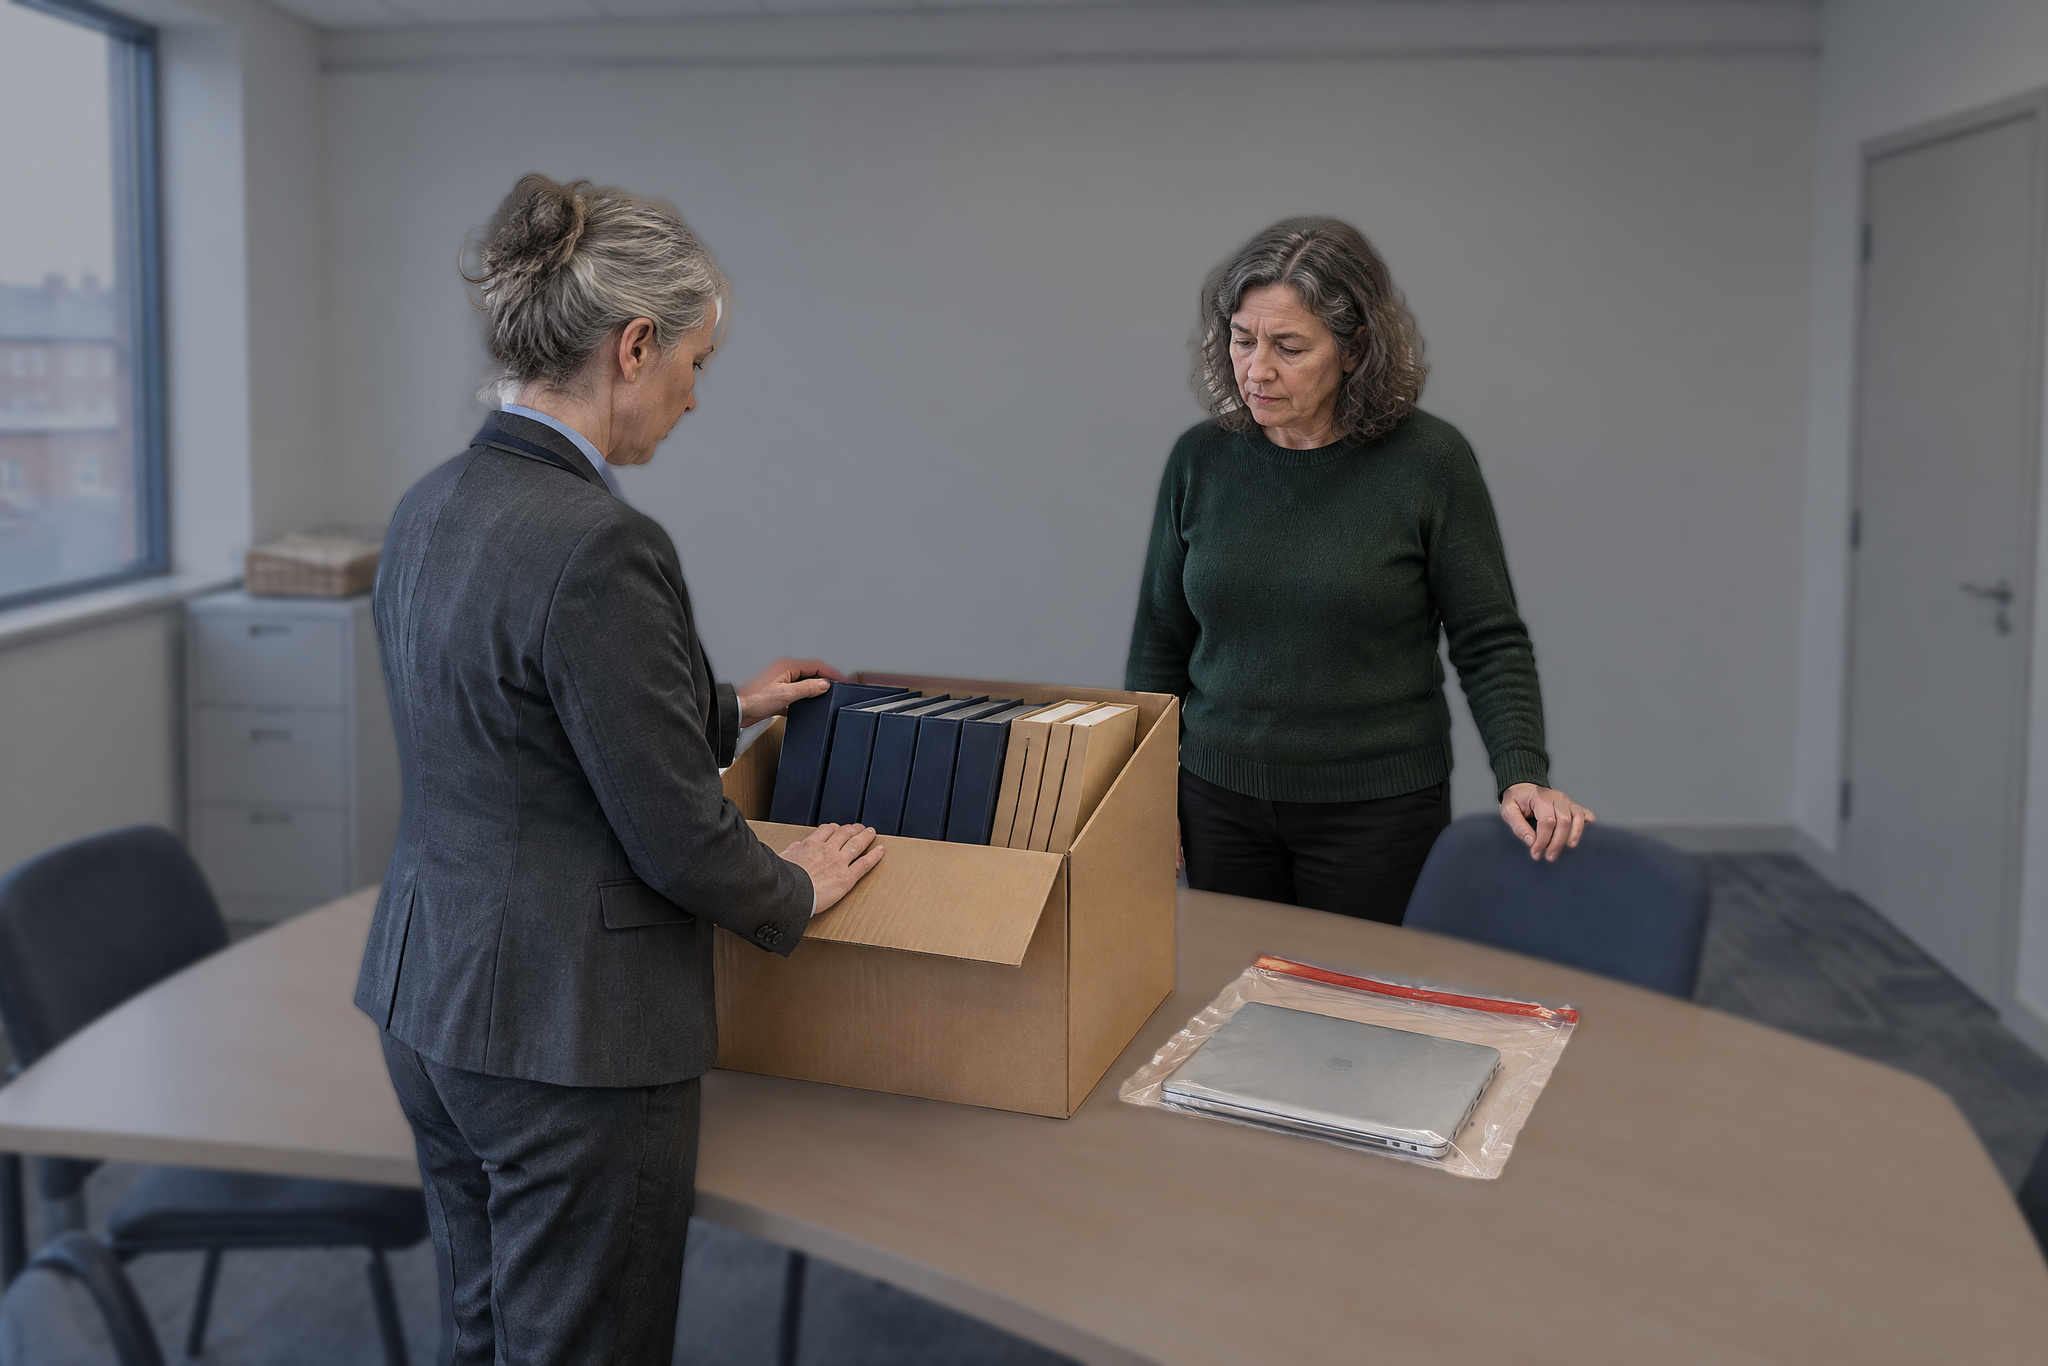
Locate and secure all records relating to the transfer.
This includes trustee meeting minutes, board minutes, any written resolutions, transfer instructions, bank records, scheme accounts and any correspondence or advice received at the time.
Cash-flow forecasts and business plans prepared around the time of the transfer may be relevant to establishing the context in which the decision was made.
Repayment records, including bank statements, transfer confirmations and any correspondence acknowledging repayment, should also be preserved.
Do not alter, delete or destroy any documents, including digital records and communications.
Do not discuss the matter using any communication channel that could be subject to disclosure.
If documents have already been requested by any authority, note what was requested and what was provided.
Why independent legal advice matters in pension fraud cases
If you are both a director and a trustee, your personal legal position is not the same as the company’s position and is not the same as the scheme’s position.
Advice given to the company by its commercial lawyers, or given to the trustees collectively by scheme advisers, will not necessarily cover your individual exposure.
You need a solicitor who advises you independently and who understands both the regulatory framework governing pension scheme trustees and the criminal law that applies to pension fraud and financial crime investigations.
A solicitor can review the documents you have preserved, assess what rules applied to your scheme and the transaction in question, advise you on how to engage with The Pensions Regulator and any police investigation, and represent you if proceedings are brought.
How a Solicitor Can Help With a Pension Fraud Allegation
A solicitor experienced in pension fraud and financial crime can advise you on the legal framework applying to your scheme and the reported transfer.
They can assess whether employer-related investment restrictions applied, whether an exemption was available and how the circumstances of the transfer, including full repayment, may affect your position.
If The Pensions Regulator has contacted you or a police investigation has begun, your solicitor can advise on your response, accompany you to an interview under caution and communicate with the relevant authorities on your behalf.
Where regulatory and criminal investigations run alongside each other, your legal representation should be coordinated across both.
If you have been reported after using pension scheme money to support your company, Ashmans Solicitors can advise on the potential allegations, your responsibilities as a trustee and the options available to you.
Speak to our Fraud and Financial Crime solicitors for advice about your position and next steps.
5 Key Takeaways
- A Regulatory breach does not automatically mean you committed fraud.
- Repaying the money in full may support your position, but it does not retrospectively make an unlawful transfer permissible or guarantee that prosecution will be avoided.
- The Pensions Regulator and police may investigate the same conduct, meaning you could face more than one enforcement process.
- If you were both a director and trustee, your responsibilities may conflict. You should obtain independent legal advice that considers your exposure in both roles.
- Preserve the original transfer records, trustee minutes, board documents and repayment evidence. T
Call us on 0333 009 6275. We are available to take your call 24 hours a day, 7 days a week.
You can also email us on enquiries@ashmanssolicitors.com or complete our Online Enquiry Form and we’ll be in touch soon.
Get in touch
We’ll respond within 15 minutes during office hours
Search our legal articles
Free expert guidance on criminal law, your rights, and what to expect at every stage.
Searching Legal Help Hub articles
Related insights and updates
Could I Be Prosecuted for False Accounting Over Accounts Supplied to a Bank?
A Restraint Order Has Frozen My Assets Before Trial: What Can Be Done?
Unexplained Wealth Order Served on a Spouse: What to Do When the Assets are in Your Name
A WhatsApp Group is Being Investigated for Insider Dealing: I Posted but Never Traded. Am I in Trouble?
What Could I Be Liable for if an Investment Service I Promoted on Instagram Collapses?
Can HMRC Freeze My Bank Account?
How to Challenge a CIFAS Marker? Step by Step Guide
CIFAS Marker Types Explained: What Your Subject Access Response Means
What Is a CIFAS Marker and How Do You Get One Removed?
Client Has Reported Me for Moving their Money Through My Account. What should I do?
A Client Reported Me to the Police for Fraud Over Building Invoices. What do I do?
Can I Be Accused of Insider Dealing Because a Family Friend Traded Shares?
I Sold a Clocked Car Without Knowing. Can I be Charged with Car Fraud?
Accused of Money Laundering but I Didn’t Know the Money was Criminal: What Is the Defence?
What Is an Unexplained Wealth Order in the UK?
Tinder Fraud in the UK: Criminal Charges, Investigations and Convictions
Seized Cash Court Order UK: How Police Obtain Cash Forfeiture Orders

Counterfeit Goods Sentencing Guidelines in the UK
How to Delete Police Records in the UK